
Unfiled returns and back taxes
Unfiled Tax Returns and Back Taxes — Get Compliant Before the IRS Acts
Years of unfiled returns feel like a wall. They are a list: work out which years actually have to be filed, pull the records the IRS already holds, file in the right order, then deal with whatever balance remains.
Firm particulars
- Attorney
- Hani H. Khatib, Attorney at Law · CPA · LL.M. (Taxation)
- Office
- 6600 W College Dr, Ste 207, Palos Heights, IL 60463
- Hours
- Monday to Friday, 9:00 a.m. to 5:00 p.m.
- Telephone
- (708) 722-2222
- info@khatiblaw.com
- Accreditation
- BBB Accredited since April 2022 · A+
Start here
Is this you?
People with unfiled tax returns usually arrive with the same two questions: how many years, and how much trouble. An unfiled tax returns attorney answers both from the IRS's own records before anything is filed. The answer to the first question is six for most people; the answer to the second depends almost entirely on whether you come forward before the IRS comes to you. Khatib Law LLC handles unfiled federal and Illinois returns for individuals and small businesses from its Palos Heights office, serving Chicago, Cook County and the southwest suburbs, as part of its tax practice.
The attorney on the file is Hani H. Khatib, Attorney at Law · CPA · LL.M. (Taxation). The compliance step is accounting; the exposure analysis, the privilege and the negotiation are law.
You stopped filing after a divorce, a business failure, an illness or a year you could not pay, and then the next year felt impossible too.
The IRS has sent notices for a year you never filed, or has already assessed tax on a return you did not prepare.
You are self-employed, nobody withheld anything, and you are not sure how large the balance will be.
A mortgage lender, immigration application or business sale is asking for returns you do not have.
Your spouse filed; you did not; and the IRS has started asking.
The duty to file never expires, and a year with no return has no statute of limitations on assessment (26 U.S.C. 6501(c)(3)). The IRS's enforcement practice is narrower. Its Policy Statement 5-133 (IRM 1.2.1.6.18), applied through IRM 5.1.11.7.1, states that enforcement of filing requirements will normally be pursued for a six-year period, and that enforcement beyond six years requires managerial approval. A revenue officer handling your case will usually ask for six years; a taxpayer coming forward voluntarily usually files six.
There are exceptions that cut both ways. A year in which the IRS has already prepared a substitute for return needs an actual return regardless of age, because the assessment is on the books and is being collected. A year with a refund that has already lapsed may not be worth filing at all if it falls outside the six and the IRS has not asked. Those decisions are made after the transcripts are in hand, not before.
Before any return is filed, the firm obtains your IRS transcripts under Form 2848. The wage and income transcript lists every W-2, 1099-NEC, 1099-INT, 1099-B, 1099-R, 1098 and similar form filed under your Social Security number, for the current year and nine prior years. The account transcript shows whether the IRS has assessed anything for a year, whether a substitute for return was prepared, what notices went out, and the date from which the collection statute runs.
This step changes the project. Someone who believes they have seven or eight bad years may find, for example, that some years show refunds, others modest balances, and one has already been assessed by the IRS on gross figures well above the real tax. The transcripts also show the gaps: a 1099-B reports gross proceeds with no basis, and reconstructing the basis is where most of the tax disappears.
When a taxpayer does not file, the IRS may prepare a substitute return from the information it holds. The IRS's own description is blunt: that return "might not give you credit for deductions and exemptions you may be entitled to receive." It uses single or married-filing-separately status, no dependents, the standard deduction only, no business expenses against 1099 income, and gross proceeds with zero basis for anything sold. The IRS then issues a notice of deficiency, and if nothing is done within 90 days the tax is assessed and collection begins.
An SFR assessment is not final in practice. Filing an accurate return for that year, with the business expenses, basis and correct filing status, replaces the SFR figure through the IRS's audit reconsideration process, and the penalties on the remaining balance are then addressed separately.
The failure-to-file penalty is 5 percent of the unpaid tax per month or part-month, up to 25 percent, with a minimum of $525 for a return due in 2026 that is more than 60 days late. The failure-to-pay penalty is 0.5 percent per month, up to 25 percent, and the two are coordinated so the combined rate is 5 percent a month for the first five months. After that only the failure-to-pay penalty continues. Interest accrues on the tax and the penalties.
Two relief routes apply. First-time abatement removes the penalties for a single year when you were penalty-free for the prior three years and are now current on filing and payment. Reasonable-cause relief applies where illness, a death in the family, a disaster, reliance on bad professional advice or similar circumstances prevented compliance. For a multi-year filer the firm requests first-time abatement for the earliest eligible year and argues reasonable cause for the rest; who qualifies and how to ask are in our article on first-time penalty abatement.
Willful failure to file a return is a misdemeanor under 26 U.S.C. 7203, carrying up to a year in prison and a fine of up to $25,000 for an individual. Prosecution is uncommon and targets willful, repeated non-filing by people with significant income. Filing voluntarily before the IRS begins an investigation is the single most protective step available, which is why these matters belong with a lawyer. The first conversation, including why the returns were not filed, is protected by the attorney-client privilege, and the narrower federal privilege for accountants does not apply to criminal matters.
Illinois requires Form IL-1040 for every year with a federal filing requirement, and the Department of Revenue receives federal return information under 26 U.S.C. 6103(d), so an unfiled federal year becomes an unfiled Illinois year. The three-year limit on an Illinois notice of deficiency (35 ILCS 5/905) runs from the date the return is filed; an unfiled year stays open.
Illinois offers a way in. Its Voluntary Disclosure Program, applied for on Form BOA-2, is open to taxpayers the Department has not already contacted or begun auditing. It limits the look-back period to four years and eliminates penalties once the tax and interest are paid within 60 days of billing. The Department's collection tools after assessment are described on the Illinois Department of Revenue page, and its authority to examine and assess is explained in our article on the Department's audit powers.
Filing turns an unknown into a number. Whatever balance the returns produce is handled with the ordinary tools: a payment plan, an offer in compromise where the numbers support one, or currently-not-collectible status. Each requires all returns to be filed first, which is why the IRS will not discuss a payment plan with a non-filer; the options are on the tax debt relief page. A balance above $66,000 (the 2026 figure, adjusted yearly) can also lead to passport denial or revocation once the IRS reports it to the State Department. That is another reason the filing and the payment arrangement are planned together.
The difference
Why an unfiled tax returns attorney who is also a CPA
One professional sees the whole list
The transcripts, the reconstruction of income and basis, the penalty analysis and the payment negotiation are one engagement, not a hand-off between the person who reconstructs the numbers and the lawyer who negotiates. Read more on the Attorney-CPA page.
Privilege from the first call
Why the returns were not filed is often the most sensitive fact in the file. Told to a lawyer to get legal advice, it is privileged, and the analysis of criminal exposure is done inside that protection. Privilege covers what you tell us to get legal advice; the figures that go onto a return, and the work of preparing it, are not privileged even when a lawyer does the work. That is why the exposure analysis is kept separate from the filing.
Reconstruction that survives review
Each missing year is reconstructed from the transcripts and your records — by your preparer or under the firm's direction — reviewed by the firm before it goes in, and filed in the order that protects you, because a return built from records rather than memory is the one the IRS accepts when it replaces a substitute-for-return assessment.
Process
How unfiled years are brought current
The consultation
Usually within the first week · about an hour · in person or by phone
Attorney Hani Khatib explains the six-year practice, the refund windows and your exposure.
Form 2848 and the transcripts
Weeks one to three · after the IRS processes the form
The firm pulls every available wage-and-income and account transcript and determines which years must be filed and in what order.
Reconstruction and filing
Usually one to three months · longer when business records must be rebuilt
Each missing year is reconstructed from the transcripts and your records — by your preparer or under the firm's direction — reviewed by the firm before it goes in, and filed in the order that protects you. Any remaining balance goes into the payment arrangement that fits.
Request a consultation
Talk it through with the attorney.
Tell us what you are facing in a sentence or two. We will tell you what the first meeting involves, and whether there is a charge for it, before you commit to anything.
Related
Related services
Tax debt relief
Can tax debt be settled for less than I owe?
You owe more than you can pay, and the letters are getting more serious. There are six ways an IRS balance ends, and each has rules, forms and a deadline.
Payment plans, offers, liens and leviesIllinois Department of Revenue
What happens if I owe the Illinois Department of Revenue?
The Illinois Department of Revenue has its own audit bureau, its own notices, its own 60-day protest clock and its own tribunal. None of it works like the IRS.
Audits, protests and the Tax TribunalAttorney and CPA
What is the difference between a tax attorney and a CPA?
Hani H. Khatib is licensed as an attorney and as a Certified Public Accountant and holds an LL.M. in Taxation. This page explains what a CPA attorney changes for you, and where the advantage ends.
Khatib Law
Questions
Questions we are asked
What happens if I have not filed taxes in years?
Three things, in sequence. The IRS matches the W-2s and 1099s it holds against the missing return and sends notices asking you to file. If you do not, it may prepare a substitute for return using that information with no deductions, credits or basis, then issue a notice of deficiency and assess the resulting tax. Once assessed, the balance goes into ordinary collection: penalties, interest, liens and levies. A year with no return has no statute of limitations, so the exposure never ages out until you file.
How many years of unfiled returns do I need to file?
The IRS's own enforcement policy, Policy Statement 5-133 (IRM 1.2.1.6.18), applied through IRM 5.1.11.7.1, says delinquency enforcement is normally pursued for a six-year period, and that going further back requires managerial approval. That is a policy, not a statute; the legal duty to file never expires and the IRS can require more years when it has reason to. In practice the firm starts with the last six years, obtains the IRS's records for all years available, and confirms the scope with the IRS where a revenue officer is already assigned.
What is a substitute for return (SFR)?
A return the IRS prepares for you from the income documents it has, as the Code allows when a taxpayer fails to file. It uses the least favorable filing status, no dependents, no itemized deductions, no business expenses and no basis for property sold. The tax it produces is almost always higher than the real figure. Filing your own accurate return for that year replaces the SFR figure, and the IRS will reconsider an SFR assessment when the actual return is submitted.
Can I still get a refund on a late return?
Only if you file within three years of the return's due date. The IRS says a refund of withholding or estimated payments, and credits such as the earned income credit, must be claimed within three years of the due date. After that the money is gone even though the duty to file remains. This is why the filing order matters: refund years are filed first, before their window closes, and balance-due years after.
Can I go to jail for unfiled returns?
Willful failure to file is a federal misdemeanor under 26 U.S.C. 7203, punishable by up to one year in prison and a fine of up to $25,000 for an individual, plus costs. Prosecutions are rare and concentrate on people with large income, repeated non-filing and evidence of intent. The more important fact is that coming forward and filing before the IRS contacts you removes most of the risk, which is why the first consultation is with a lawyer: what you tell us to get legal advice is privileged, although the figures that go onto a return are not.
How do I get my IRS wage and income transcripts?
Through an IRS Individual Online Account, by mailing Form 4506-T, or by having your representative request them under Form 2848. The wage and income transcript lists every W-2, 1099, 1098 and similar form reported to the IRS under your Social Security number, and it is available for the current year and nine prior years. The account transcript shows what the IRS has assessed and when. Together they tell us what the IRS already knows and what each missing year looks like.
What penalties apply to late filing and late payment?
The failure-to-file penalty is 5 percent of the unpaid tax for each month or part of a month the return is late, capped at 25 percent; if the return is more than 60 days late the minimum is $525 for returns due in 2026. The failure-to-pay penalty is 0.5 percent a month, also capped at 25 percent, and the two are coordinated so the combined monthly rate is 5 percent for the first five months. Interest runs in addition. First-time abatement can remove the penalties for one year if you were penalty-free for the prior three, and reasonable cause can remove them where you can show why you could not comply.
Does Illinois also require the back returns?
Yes. Illinois residents with a federal filing requirement must file Form IL-1040 for the same years. The IRS shares return information with state revenue departments (26 U.S.C. 6103(d)), and the three-year limit on an Illinois notice of deficiency runs from the date a return is filed, so an unfiled Illinois year stays open indefinitely. Illinois also has a Voluntary Disclosure Program: if the Department has not already contacted you, it limits the look-back to four years and waives penalties once the tax and interest are paid.
Your attorney
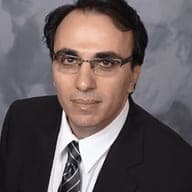
Hani H. Khatib
Attorney at Law · CPA · LL.M. (Taxation)
Founder and managing attorney of Khatib Law LLC, established in Palos Heights in 2017. An attorney licensed in Illinois and a Certified Public Accountant, he concentrates his practice in estate planning, real estate, tax controversy and small-business matters. About Hani Khatib
Request a consultation
Tell us what you are facing.
A sentence or two is enough to start. We will tell you what the first meeting involves, and whether there is a charge for it, before you commit to anything.
(708) 722-2222
Monday to Friday, 9:00 a.m. to 5:00 p.m. · 6600 W College Dr, Ste 207, Palos Heights
What happens next
Your message goes to the firm’s office, not a call centre.
If you mention a deadline, it is read first.
We run a conflicts check and, if we can help, call or email you to set a time.
We confirm the kind of matter and what the first meeting involves, including whether there is a charge for it.
If we go forward, you receive a written engagement letter.
Scope and fee basis in writing before any work begins. Please do not email documents until we have confirmed an engagement in writing.
What to bring to the first meeting
- A list of the years you believe are unfiled, even if it is only a guess; the IRS transcripts will confirm it.
- Every IRS or Illinois letter about those years, including any notice that a return was prepared for you.
- The W-2s, 1099s and 1098s you still have, and the names of employers, payers, banks and brokers for the missing ones.
- Bank statements for any year with self-employment income, so expenses can be reconstructed.
- The last return you did file.